Anyone trying to manage household spending soon discovers that a plan only works if it is followed. Cash envelopes offer a physical way to set limits, while digital budget apps link accounts, categorize purchases and send reminders. Both methods can help people spend with more intention, and both carry costs that are easy to overlook at the start.
Both methods are weighed here in broad terms. Nothing in the comparison amounts to financial advice or a product recommendation, and no particular outcome is promised. The goal is to help a reader see what each method gives up in control, effort and privacy, so that the choice fits daily life rather than an ideal routine.
Tactile Control Versus Automation
Cash envelopes make limits visible. When the envelope for groceries is empty, the household knows the food budget is finished for the period, and that moment of friction can change behavior quickly. Readers may also want to visit under-news.com. Irregular bills such as repairs or gifts are often the place where a plan first wobbles.
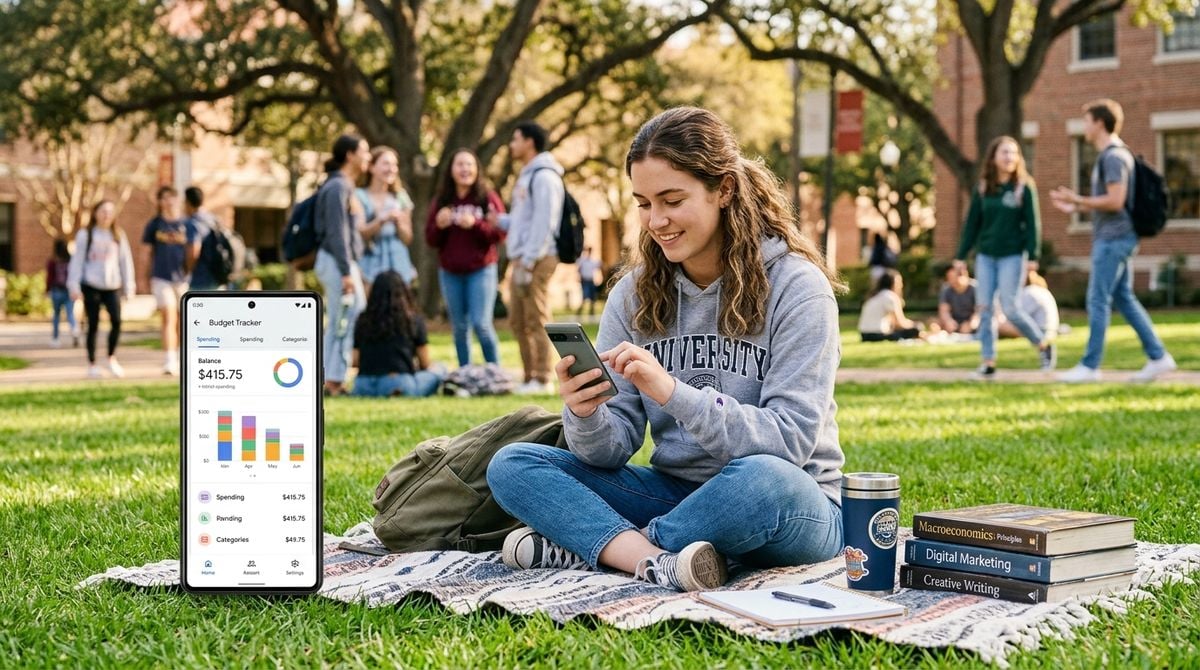
Digital tools trade that physical feeling for automation. Transactions appear on their own, categories update in the background and alerts can warn about unusual charges. The advantage is less manual work, but the risk is that people stop looking closely. A reminder on the screen is easy to dismiss, while an empty envelope is hard to ignore. Many people find that the physical act of paying into an envelope builds a memorable pause before each purchase.
Detail, Time and Attention
Detail is where the two methods diverge. Envelopes track only what was placed inside them, so they show broad categories but rarely capture every small purchase. Apps can break spending into fine groups and produce charts, which helps spot patterns. Those charts take attention, however, and a person who checks them daily may spend more time reviewing numbers than adjusting habits. You can also visit Chronicules.com for more reading.
Set-up effort also differs. Envelopes need a regular withdrawal, labels and a refill routine, which is simple but demands discipline at the bank counter. Apps need account links, category choices and occasional corrections when a transaction is misfiled. Neither task is hard, but both need regular upkeep to remain useful over the long run. A monthly sit down with the records can keep both methods honest, whichever one a household chooses.
Shared Households and Privacy
Households that share money face extra questions. Cash in envelopes is visible to everyone who can see the drawer, and that openness can build trust, but it also means the system depends on honest handling. Digital apps can allow each partner a separate login and clear permissions, though sharing account access raises privacy concerns that deserve thought. For a related read on this site, see Owning or Borrowing Sports and Garden Equipment.
Privacy also depends on what the app collects and how it uses the data. Read the policy before linking accounts, and prefer tools that let you limit access to the parts you need. Some people prefer a cash only approach precisely because it keeps spending details away from third parties. That preference is valid and worth respecting when choosing a method. Agreeing on what each partner needs to see can prevent awkward conversations later.
Choosing a Method You Will Keep Using
The best method is the one that survives an ordinary week. A plan that looks elegant on a weekend can collapse during a busy stretch when nobody has time to reconcile receipts. Start with the simplest version that addresses the main problem, and add detail only when the first version runs smoothly. Small wins build the habit that large systems often fail to create. Sticking with a small routine for several weeks reveals more about fit than any amount of planning on paper.
Revisit the choice when income, household size or goals change. A method that worked during one stage of life may feel cumbersome during another. Combining approaches is also reasonable, such as using envelopes for a few flexible categories while an app tracks the rest. The aim is steady awareness of spending, not a perfect spreadsheet. If one method feels like a chore, that is a sign to simplify rather than to blame yourself for falling behind.
Cash envelopes and digital budget apps both put a plan in front of you, but they ask for different kinds of attention. The envelope favors tangible limits and simplicity, while the app favors detail and automation. Choosing well means being honest about the effort you will actually sustain, and then building a routine that fits your home. A few honest check ins each season will show whether the chosen method still does its job.