Money in a household rarely feels like a single problem. It shows up as a pile of statements on the kitchen counter, a few unexpected charges, a conversation that turns tense about groceries and a quiet worry that lingers after the bills are paid. Many people try to fix their budget by pulling up one spreadsheet at a time, yet the signals that matter most often appear in the way the month feels. Looking at the numbers with care, listening to the everyday habits around the house and noticing the stress that builds during tight weeks can all help you plan with more clarity.
This article offers general ideas about personal money habits. It is not financial advice and does not recommend any specific product or strategy. Every household has its own needs and obligations, so use these observations as a way to notice patterns that deserve a closer look.
Looking at the Monthly Statement
Begin with the statement that arrives each month, whether it comes from a bank, a card provider or a payment app. Scan the list of transactions and group them into simple categories such as housing, food, transport, subscriptions and savings. A few minutes of sorting often reveals spending that never felt like a choice, such as a service renewed automatically or a membership nobody uses. Readers may also want to visit commentsdb.com.
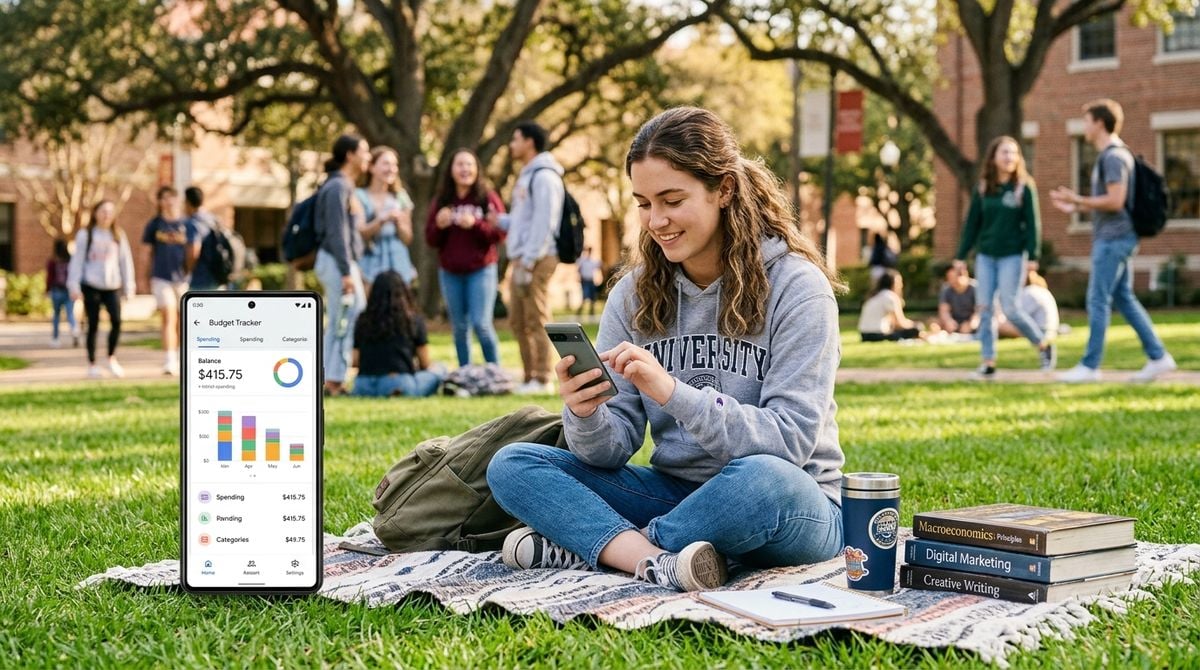
Look for the shape of the month rather than the total alone. Do the largest payments cluster near the start, leaving the second half thin? Do small purchases creep up on weekends? A chart or a simple color code can make those shapes obvious. Once you see the pattern, you can decide whether it reflects your priorities or simply the way the calendar happens to fall.
Listening to Your Spending Habits
The habits in a household have a sound of their own. Notice how often someone suggests that a purchase can wait, how many times the phone pings with a delivery notice or whether conversations about money end quickly. Those small moments tell you how comfortable the household is with planning. A calm discussion about a shared goal usually leads to better choices than a rushed argument at the checkout.
Listen to the questions you ask yourself before buying something. Do you hear a voice that says the purchase is needed, or one that says it would be nice to have? Writing down those reactions for a week can clarify what drives your spending. You can also visit bajiroo.com for more reading.
Feeling the Stress of Tight Weeks
Pay attention to how the budget feels in your body during the weeks when money runs short. For a related read on this site, see Budget Apps Under the Senses Test: What Looks. Tight shoulders, a habit of checking the bank app too often or a reluctance to open bills can all signal stress that needs a plan. Stress tends to push people toward quick fixes, such as skipping savings or relying on a card for basic groceries. Naming the feeling is a useful first step toward handling it.
Consider a small cushion for those tight weeks. A modest amount set aside each cycle can soften surprises, such as a school fee or a repair bill. Even when the sum is small, having it available often reduces the urge to make rushed decisions. Share the plan with a partner or family member, so the responsibility feels shared rather than private.
Adjusting Before the Next Cycle
At the end of each month, decide on one or two changes rather than rewriting everything. You might cancel an unused subscription, move a bill to a different date, or set a limit for takeaway meals. Write the change down, then watch it for a full cycle before judging the result. Small steps are easier to sustain than dramatic overhauls that collapse after two weeks.
Try a simple experiment for one month. Choose a single category, such as eating out or fuel, and track it closely each day. Write down what you bought and how you felt when you paid. Many people discover that a small habit, repeated often, adds up to a surprising sum. The exercise is not about cutting joy from life. It is about making sure the money you spend matches the things you value most.
Once the experiment ends, decide what to keep. Some changes will feel easy, while others will feel uncomfortable, and both reactions are useful information. Share the results with the people in your home so everyone understands the reasons behind the new habits. A household that talks about money openly usually feels less tense about it.
Keep the review gentle. The goal is not to punish yourself for spending but to understand where money goes and how that spending affects daily life. When the numbers, the household conversations and the feeling of the month begin to line up, planning becomes less stressful and more rewarding. Repeat the review each month, and the budget will gradually reflect the life you actually want to live.