
Undertaking a comprehensive home renovation represents a significant capital outlay for any property owner. Unlike conventional recurring bills or predictable asset purchases, large-scale property updates are characterized by fluctuating material costs, shifting contractor schedules, and unexpected structural discoveries. For homeowners managing personal balance sheets, maintaining steady liquidity throughout the lifecycle of a construction project requires rigorous financial discipline. Without a deliberate cash management framework, renovation expenses can swiftly erode liquid savings and destabilize broader household solvency.
Navigating a residential overhaul successfully involves viewing the property not merely as a family living space, but as a physical asset requiring structured capital deployment. By establishing disciplined funding tiers, categorizing improvements by functional urgency, and staging cash outflows alongside construction milestones, property owners can safeguard their liquidity while achieving their architectural goals.
Structuring a Dedicated Renovation Reserve Fund
The foundation of sound renovation cash management begins with the separation of project funds from ordinary household operating accounts. Commingling renovation capital with everyday checking balances creates an inaccurate picture of available spending capacity. Establishing an independent project account ensures that capital earmarked for structural work remains protected from discretionary household spending.
Equally critical is establishing a distinct contingency reserve that remains untouched until legitimate construction emergencies arise. Unforeseen electrical wiring updates, subfloor decay, or plumbing re-routes inevitably appear once walls are opened. Rather than scrambling for short-term credit solutions when surprises emerge, maintaining earmarked contingency reserves prevents expensive financing expenses and project stalls.
Strategic capital allocation also requires understanding how different types of improvements influence overall property worth. Property owners who balance structural improvements with marketability frequently consult our overview on staging and furnishing investment real estate to understand how presentation connects to market valuation. Aligning expenditure with clear equity goals ensures every dollar spent contributes to long-term financial resilience.
Prioritizing Structural Integrity Before Aesthetic Finishes
A common financial mistake in residential renovation is pouring capital into visible, cosmetic features while neglecting underlying infrastructure. High-end cabinetry, stone countertops, and designer fixtures offer visual appeal, but they provide little long-term value if installed over deteriorating framing or alongside aging plumbing lines. Allocating resources to core building systems preserves the baseline value of the asset and protects subsequent decorative work from premature damage.
Foundational health includes evaluating the roof, exterior drainage, moisture barriers, and thermal insulation. Upgrading electrical service panels and replacing fragile pipe networks should consistently precede interior decorative enhancements. When structural repairs are deferred in favor of visual updates, homeowners face the risk of having to demolish newly installed finishes later to address hidden system failures, multiplying labor and material expenditures.
Before committing capital to surface-level changes, homeowners must verify that foundational building envelopes and primary mechanicals are thoroughly sound. Practical home management resources like homesmoving.org emphasize the importance of structural durability and dependable construction systems when maintaining a property over time. Ensuring that a residence is robust and reliable creates a dependable foundation for subsequent interior enhancements.
Phasing Interior Updates to Protect Monthly Liquidity
Attempting to overhaul an entire residence in a single sweeping initiative places immense strain on liquid reserves. Phasing interior renovations across distinct stages allows household cash flow to recover between project milestones. By grouping related rooms or distinct functional spaces together, homeowners can finance subsequent phases out of ongoing earnings rather than relying heavily on debt financing or asset liquidations.
When prioritizing spaces, focus on high-utility areas that directly support daily productivity and domestic function. Modernizing kitchens and primary bathrooms often yields the highest functional return, whereas secondary living areas, finished basements, and guest rooms can remain in queue until primary construction disbursements are settled and cash reserves are replenished.
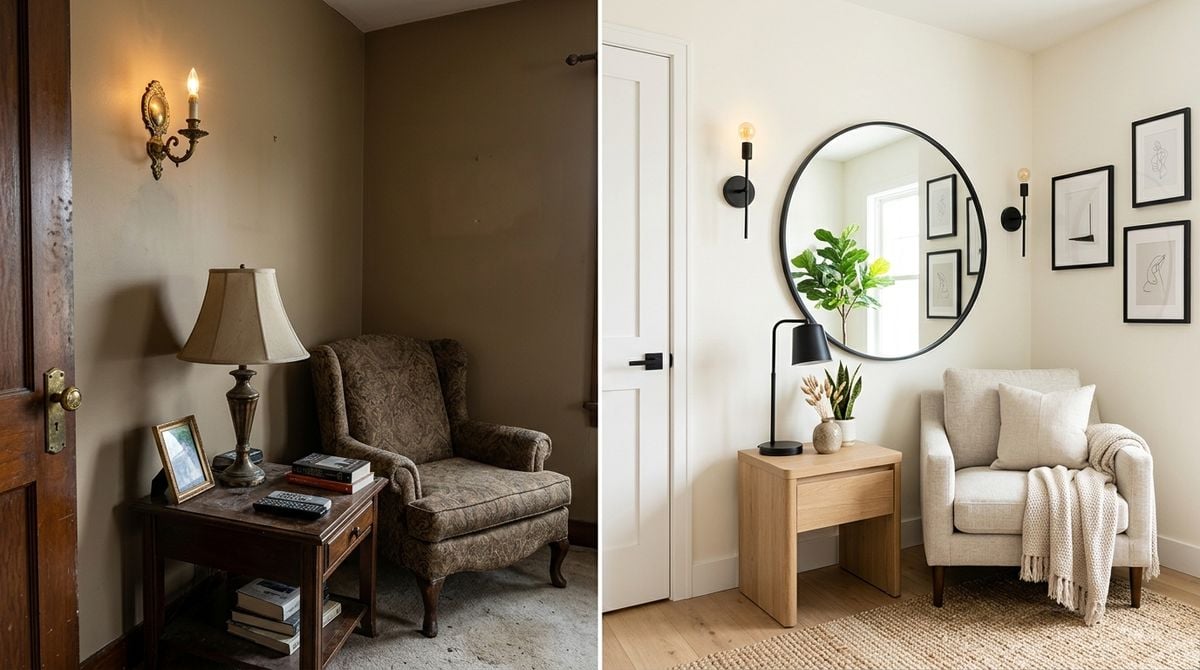
When homeowners reach the point of transforming daily living environments, organizing interior priorities prevents budget exhaustion. Exploring design guidance and conceptual planning through Exxointerior.com allows property owners to clarify layout intentions and decorative upgrades before issuing purchase orders for materials. Thoughtful visual planning before ordering materials prevents expensive design revisions and restocking fees mid-stride.
Establishing Contractor Milestone Contracts and Contingency Protocols
Contractual payment structures represent the primary lever for controlling renovation cash flow. Avoid releasing substantial funds upfront before work commences on site. Standard financial discipline dictates tying disbursements to clearly defined, verifiable construction milestones, such as foundation sign-offs, framing completion, rough-in mechanical inspections, or finished surface installations.
Retaining a defined portion of each progress payment until final project delivery provides leverage to ensure that punch-list items and final inspections are thoroughly completed. Furthermore, all scope adjustments should be governed by formal change orders that outline specific cost implications and schedule modifications prior to authorizing any new work.
A structured financial checklist helps keep contractor commitments aligned with available capital:
- Establish a signed payment schedule tied strictly to completed and verified building milestones.
- Withhold a retainage balance until all final permits, punch-list tasks, and cleanup are confirmed.
- Require written change orders with explicit line-item costs before authorizing deviations.
- Verify that contractor insurance policies and municipal permits are active before issuing funds.
- Track all material receipts and labor draws in a central ledger against the original project estimate.
Managing Household Transition and Carrying Expenses
Beyond direct construction labor and materials, secondary carrying costs frequently jeopardize renovation budgets. If major structural alterations force occupants to vacate the residence temporarily, alternative living expenses such as short-term rental leases, double utility payments, storage unit fees, and moving logistics can accumulate rapidly.
Failing to incorporate these auxiliary living expenses into the master project budget forces households to pull funds from their structural contingency reserves. Property owners should forecast carrying costs alongside their primary construction schedule, accounting for the reality that construction timelines often extend beyond original target completion dates due to supply chain variability or municipal inspection bottlenecks.
Maintaining personal financial equilibrium throughout a renovation requires continuous monitoring of these parallel living costs. Keeping auxiliary expenses lean ensures that liquid reserves remain dedicated to completing the physical build rather than sustaining prolonged administrative overhead.
Disciplined cash management during a substantial residential renovation is fundamentally about balance, foresight, and risk management. By establishing dedicated reserve funds, addressing structural reliability before cosmetic upgrades, and controlling contractor disbursements through milestone contracts, homeowners can transform their living spaces without compromising their broader financial stability. A successful renovation not only delivers a revitalized, functional home, but it also leaves household balance sheets intact and prepared for long-term growth.