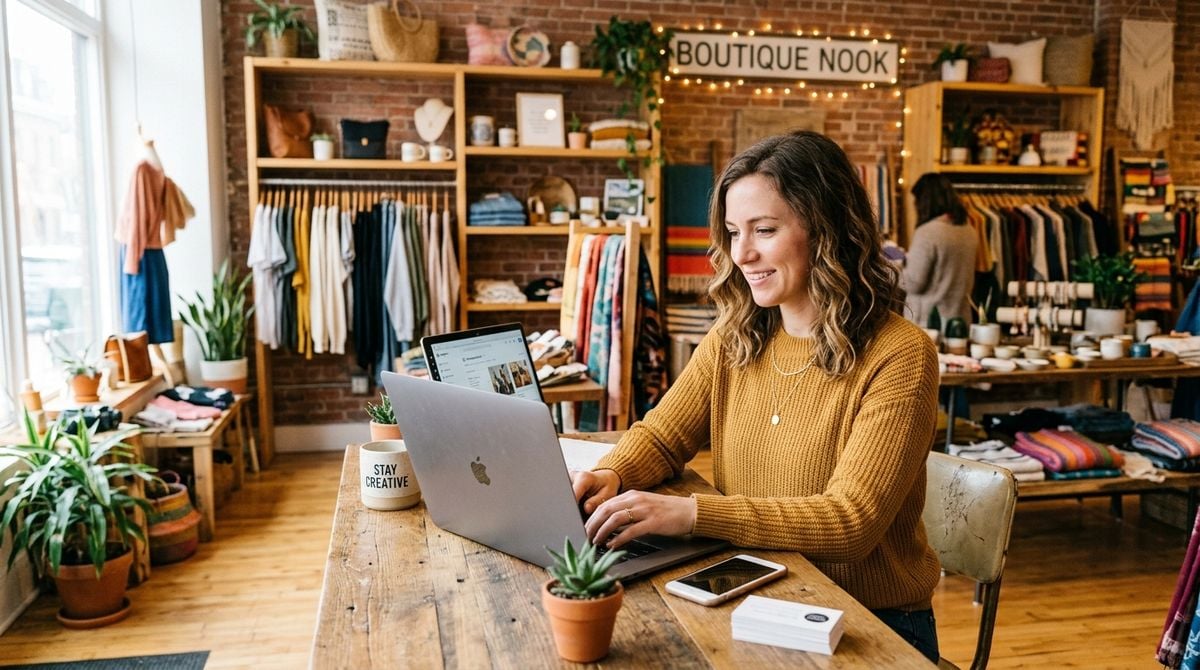
Launching an independent retail boutique focused on curated clothing, cosmetics, and accessories is an ambitious endeavor that blends creative taste with rigorous fiscal discipline. While the appeal of curating apparel and skincare lines attracts many entrepreneurs, building a sustainable enterprise requires a clear commercial structure. Many new boutique ventures struggle not because of a lack of aesthetic vision, but due to insufficient capitalization and poor cash allocation before the business reaches break-even status. Establishing a sound financial blueprint allows emerging boutique operators to navigate early overhead expenses, establish reliable supplier relationships, and keep their storefronts viable through shifts in consumer demand.
Entrepreneurs entering this space must treat capital preservation as an ongoing operational priority rather than a single upfront calculation. Retail operations involve front-loaded costs that cannot be easily recouped if inventory does not move at anticipated margins. By structuring startup funds thoughtfully, prospective shop owners can safeguard their ventures against common retail bottlenecks and position themselves for durable growth.
Estimating Startup Costs for Retail Space and Inventory
Opening a physical or hybrid boutique requires budgeting across several core operational areas, beginning with physical premises and foundational stock. Securing commercial real estate typically demands initial lease deposits, store build-out expenditures, and funds for interior fixtures such as display racks, shelving, lighting, and point-of-sale hardware. In addition to property costs, boutique owners must allocate substantial capital toward opening stock orders, packaging supplies, and merchant processing systems.
While aspiring owners often understand budgeting for professional wardrobe and grooming when managing personal attire, transitioning to commercial scale requires a fundamentally different framework. Personal shoppers buy for individual utility, whereas commercial retailers purchase goods with the sole intention of generating profitable turnover. Underestimating the amount of working capital tied up in wholesale inventory can leave a boutique vulnerable to supplier payment deadlines before customer sales have materialized. Maintaining separate business accounts, calculating shipping and freight tariffs into unit costs, and negotiating structured payment terms with distributors are foundational steps for keeping startup obligations manageable.
Managing Cash Flow Across Seasonal Purchasing Cycles
Cash flow management in fashion and beauty retail is heavily influenced by delivery calendars and seasonal transitions. Designers and beauty manufacturers operate on lead times that require boutique owners to commit capital and place wholesale orders months ahead of the selling period. This operational lag means money leaves the business account long before seasonal items appear on the shelves or generate revenue.
To manage this rhythm without exhausting reserves, boutique owners should implement rolling cash projections that track weekly inflows and outflows. Maintaining a conservative purchasing calendar helps avoid inventory crunches during intermediate periods when older stock is being cleared to make room for fresh arrivals. Clear inventory turnover tracking helps owners identify slow-moving product lines early, allowing for timely floor adjustments before capital becomes trapped in obsolete merchandise. Managing vendor terms carefully, such as requesting phased shipment deliveries, also relieves cash strain during slower retail periods.
Evaluating Financing Options for Boutique Entrepreneurs
Finding appropriate capital to start and sustain a retail shop requires evaluating several funding avenues, each carrying distinct structural responsibilities. Relying solely on personal savings can deplete emergency cushions, while excessive debt obligations can strain early operating income. Diversifying funding sources helps founders balance flexibility with long-term financial liability.
Boutique entrepreneurs generally consider several traditional and modern financing methods:
- Commercial bank term loans and credit union financing designed for small enterprise equipment and store build-outs.
- Government-backed microloans and local community development funds that support neighborhood retail revitalization.
- Dedicated business lines of credit intended to bridge temporary working capital gaps between wholesale orders.
- Vendor trade credit agreements that permit payment for shipments after delivery rather than upfront.
Selecting the right financing mix depends on the boutique’s operational model and repayment capacity. Debt that requires immediate monthly service can create severe stress during the opening phases of retail, so facilities with flexible draw terms or deferred schedules are often preferable. Regardless of the chosen vehicle, securing funding requires a detailed operational plan, realistic revenue expectations, and transparent expense forecasts that demonstrate how borrowed funds will directly support inventory turnover.
Tracking Market Movements to Avoid Dead Stock
In both apparel and cosmetic retail, product obsolescence represents one of the largest hazards to gross margins. Stock that fails to sell quickly takes up valuable floor space, ties up liquidity, and often requires steep markdowns that erode profitability. Successful retailers combine disciplined financial analysis with consistent awareness of emerging trends to ensure purchasing decisions align with consumer interest.
To keep buying strategies aligned with genuine customer preferences, merchants should monitor broader fashion shifts alongside direct store sales data. Independent research through style platforms such as fashionlifeslylenews.com provides early insight into emerging color palettes, lifestyle accessories, and styling trends before they reach saturation. By identifying rising demand patterns early, boutique buyers can test small product batches with limited initial commitments rather than ordering heavy volume upfront.
Similarly, keeping pace with contemporary cosmetic preferences helps store owners select high-margin skincare and makeup lines that resonate with modern shoppers. Regularly reviewing consumer insights on portals like luvlybeauty.com assists retailers in discovering fashionable beauty products and identifying which lines are sustaining strong market momentum. Using real-time trend observation as an inventory risk management tool prevents overcommitting capital to fading fads, keeping operating cash available for proven sellers.
Building Working Capital Reserves for Long-Term Stability
A boutique’s survival over its opening phases frequently hinges on the size and discipline of its reserve fund. Retail revenues naturally fluctuate due to local foot traffic changes, economic shifts, and seasonal weather variations. Without an unencumbered cash cushion, even a minor dip in monthly receipts can interfere with rent payments, payroll commitments, or upcoming wholesale inventory deposits.
Establishing a dedicated cash buffer should be treated as a fixed monthly business expense rather than a secondary priority when profits are high. Allocating a steady portion of gross operating receipts directly into a liquid reserve account insulates the enterprise against unexpected fixture repairs, supply chain delays, or supplier price increases. Having dependable working capital also enables boutique operators to seize opportune closeout discounts or exclusive collection offerings that competitors without cash cannot pursue. Over time, this disciplined accumulation of liquid reserves transforms an early-stage shop into an enduring, adaptable commercial business.
Financing and maintaining an independent fashion and beauty boutique is a continual balance between creative product curation and methodical money management. By accurately projecting initial expenses, maintaining vigilance over cash flow cycles, and utilizing market research to mitigate inventory exposure, entrepreneurs can build a resilient retail presence. Grounding everyday buying and merchandising decisions in clear financial boundaries provides the stability required to serve customers and sustain operations over the long term.