Purchasing or constructing a brand-new residence represents a major personal achievement, yet many new homeowners find themselves facing an unexpected cash squeeze immediately after receiving the keys. The closing process naturally consumes substantial liquidity, from earnest money and down payments to closing fees and moving expenses. Once the moving truck pulls away, the reality of an echoing, unfurnished property sets in. Empty rooms demand basic window coverings, light fixtures, area rugs, and practical furnishings to become truly functional living environments.
Without an intentional spending framework, these post-move outlays can quickly strain personal finances. Retail credit cards and impulse purchases often fill the void, creating high-interest balances before the first mortgage payment is even due. Navigating this transition smoothly requires treating the finishing stages of a home as a distinct financial project. By separating move-in necessities from purely cosmetic desires, buyers can establish a comfortable living space while keeping their overall household budget grounded and resilient.
Separating Structural Commitments From Move-In Needs
A common budgeting misstep during residential construction is assuming that standard builder handoffs produce a turnkey living environment. Standard construction contracts typically guarantee code compliance, functional plumbing, baseline kitchen cabinetry, and standard flooring. However, builder packages rarely provide custom window treatments, adequate closet storage systems, or personalized task lighting. If these items are not accounted for early in the planning process, new owners must scramble to cover them out of pocket.
When planning a major residential build or extensive property customization, prospective owners benefit from looking closely at the full construction timeline. Exploring comprehensive resources such as allhomedecors.com helps future occupants grasp what it takes to construct a functional dream home, shedding light on the steps involved in planning a living space from the ground up. Recognizing where structural construction boundaries end allows you to establish a separate, realistic financial boundary for post-handover outfitting.
Maintaining this boundary ensures that unexpected construction overruns do not silently devour your finishing fund. When change orders or unforeseen building delays occur, builders pull from contingency reserves. If you have kept your move-in outfitting capital strictly segregated in a dedicated savings account, you will still possess the resources necessary to make the home livable on move-in day.
Categorizing Immediate Essentials Versus Long-Term Additions
Attempting to complete an entire house at once is the fastest way to exhaust cash reserves. Instead, practical homeowners divide their immediate post-closing needs into distinct tiers. The primary tier consists of elements required for privacy, safety, and basic daily comfort. The secondary tier encompasses non-essential aesthetic upgrades, decorative accents, and secondary room setups that can wait until savings balances recover.
Before buying decorative accessories or styling secondary guest spaces, direct available funds toward foundational items that support healthy day-to-day living:
- Window coverings for street-facing rooms to ensure immediate privacy and light management
- Primary sleeping and dining furniture that allows family members to rest and eat comfortably
- Basic laundry, cleaning, and essential kitchen organizational tools
- Adequate ambient lighting in rooms where builder-grade fixtures fall short
By addressing these core elements first, you create a baseline of stability. Rooms that serve secondary purposes, such as formal dining rooms or guest bedrooms, can remain sparsely furnished or empty for several seasons. Living in the home for a while also reveals how your household actually uses each space, which often prevents expensive decorating missteps that look attractive in showrooms but fail in everyday practice.
Finding Visual Cohesion Before Spending
Rushing to fill vacant rooms often leads to disjointed purchasing decisions. When owners buy furniture piece by piece without an overarching layout strategy, they risk ending up with mismatched styles, awkward spatial flow, and buyer remorse. Spending time gathering visual inspiration and clarifying room proportions is completely free, making it the most cost-effective early step in the interior setup process.
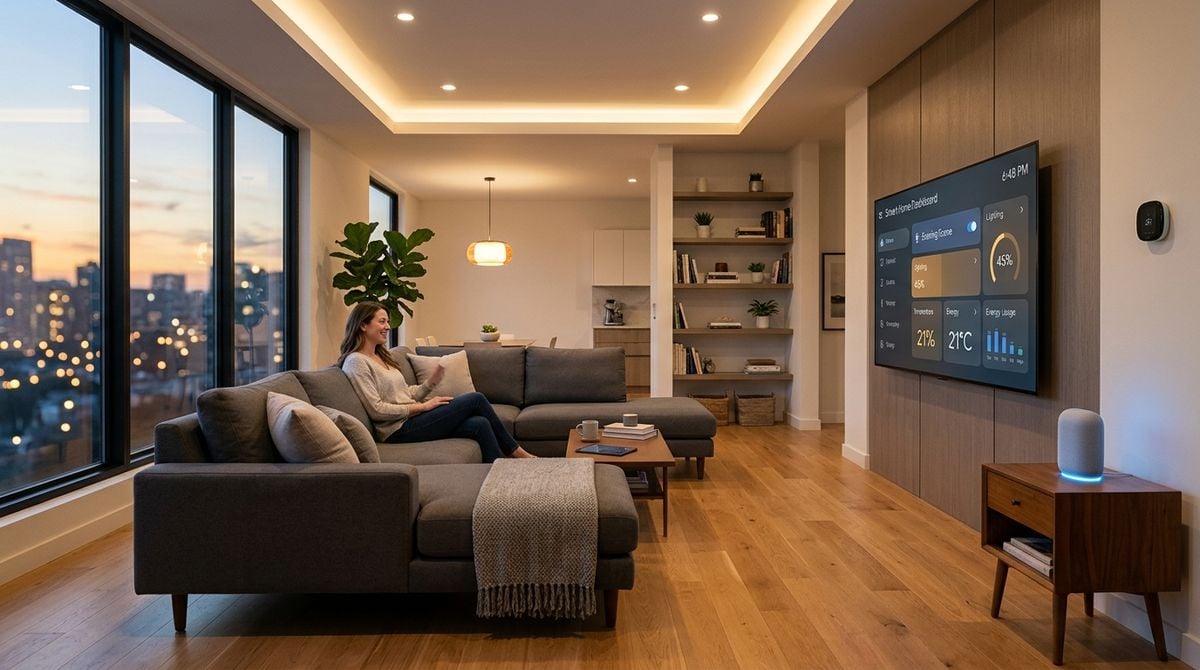
Studying thoughtful room arrangements provides clarity on how different textures, colors, and furniture scales interact before any purchase occurs. Looking through photo collections and design showcases on Groliehome gives homeowners a clear sense of how to balance living rooms, kitchens, and bedrooms into cohesive, visually appealing environments. Developing a clear concept across your primary living areas ensures that every item purchased down the line fits into a unified, enduring aesthetic.
Once you establish a cohesive design plan, create a simple master inventory of pieces you need. Having a specific list prevents impulse shopping during weekend retail sales. If an appealing item does not align with your broader layout or fill an identified functional gap, it stays in the store, keeping your capital safe for true priorities.
Funding Options for Secondary Interior Investments
Financing the decorative and practical layers of a home requires disciplined cash management. While borrowing options such as personal lines of credit or retail promotional financing are readily available, relying heavily on debt to style a home increases ongoing monthly commitments during a period when property taxes, insurance, and utility bills may still be stabilizing. Relying primarily on structured cash accumulation remains the most predictable route.
Some households prefer to establish a dedicated sinking fund, setting aside a set amount from each paycheck specifically earmarked for home improvements. For those evaluating structured approaches to funding larger cosmetic changes across several rooms, our guide on financing strategic interior decor updates explores sensible methods for handling balance sheets during interior overhauls. Pairing methodical cash reserves with realistic timelines shields you from accumulated interest charges.
Another effective tactic is exploring secondary markets and local surplus builders. Quality solid-wood furniture, architectural hardware, and high-grade light fixtures can frequently be acquired through regional secondhand avenues or warehouse clear-outs. Reinvesting sweat equity by cleaning, refinishing, or assembling these pieces yourself stretches your available dollars much further than buying retail packages.
Establishing a Sustainable Timeline for Future Enhancements
Social pressure and modern media often create an unrealistic expectation that a home must look magazine-ready on the day of arrival. In reality, creating a balanced, personal living space is a multi-stage process that unfolds naturally over months or years. Embracing an extended timeline removes the financial urgency that leads to debt accumulation and buyer fatigue.
Pacing your interior investments allows you to observe seasonal light changes, evaluate practical storage bottlenecks, and adapt your floor plan to how you genuinely live. By maintaining an organized spending plan, honoring your core essentials, and allowing non-critical updates to develop gradually, you protect your broader financial health while turning a newly constructed structure into an enduring, comfortable home.