Tracking household money does not require a large collection of software. Most families do well with a spreadsheet, a notebook for quick entries, a calendar for bill dates and a folder for receipts. Each tool does one job, and together they give a clear picture of where money goes. The aim is steady awareness rather than perfect detail, so the stack should be light enough that it gets used every week. A tool that is opened once a month rarely changes behavior, while a short weekly check builds a clear habit over time.
Start with the questions you need answered. Do you want to know total monthly spending, the cost of a single category, or the timing of bills? Those answers decide which tools are necessary. A stack built from real questions stays focused, while one built from a catalog of features tends to collect dust after a few busy weeks. Write the top three questions at the head of the spreadsheet, so the answers are always visible when you open it.
A Spreadsheet and a Notebook
A plain spreadsheet with columns for date, category, amount and note handles most household tracking. Keep the category list short, perhaps six or seven entries, so that each expense is easy to place. Add a summary tab that totals each category at the end of the month. Freeze the header row so the column names stay visible when the list grows past a single screen. A small set of formulas is enough, and nothing needs to be elaborate.
Readers may also want to visit usacommercedaily.com. Look for guides that show how to set up monthly totals without complicated macros. A notebook beside the kitchen table works well for quick entries, since a receipt jotted down at the shop can be copied into the sheet later in the evening. Keep a pencil with the notebook, so no entry is lost because the pen ran dry.
Receipt Scanning Apps
A receipt scanning app can save time when paper slips pile up. Photograph each receipt as soon as you get it, and store the image in a dedicated folder named by month. Keep the originals until the entries are confirmed, then recycle the paper if the store and your household do not need it for returns.
For a related read on this site, see Upgrading a Home in Stages Without Straining the. Scanning is only useful if the numbers are checked, so take a few minutes each week to compare the sheet with the statement. A quick reconciliation catches typing errors before they grow into confusion at the end of the quarter.
Calendar Reminders for Bills
A calendar with reminders is one of the most useful money tools in the home. Enter each bill due date as a recurring event, and set a reminder a few days before payment is due. Include subscriptions, insurance and any seasonal charges, so nothing arrives as a surprise on a busy weekend.
Grouping bills by week so that cash flow stays steady is explained in this practical website on household bill planning. Keep the reminders simple and avoid duplicating them across several apps. One calendar that everyone in the household can see is more reliable than three competing alerts. Give each recurring payment one clear name, so the reminder explains itself without a second look.
Subscriptions and Gadgets to Skip
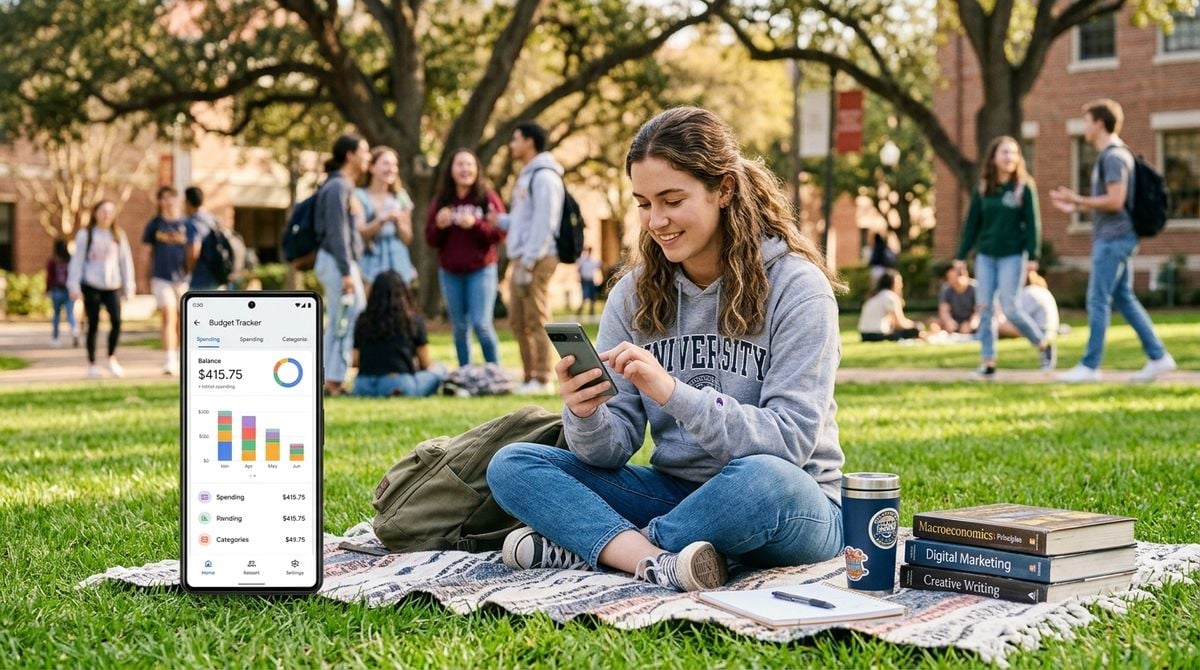
Several money tools add clutter without adding clarity. Budgeting apps that ask for bank logins, connect many accounts and generate long reports can be tempting, yet many users stop opening them after a short trial. Elaborate dashboards with dozens of charts rarely change a household decision, because the key facts fit on one page.
Subscriptions that track other subscriptions can also become a trap. Review your list of recurring charges once in a while, and cancel any service you no longer use. Check the same list before each holiday season, since new subscriptions often start quietly during busy months. A stack that stays small is easier to maintain and less likely to share information you did not mean to expose.
Backing Up the Money Files
Money records are valuable, so keep them safe. Save the spreadsheet in two places, such as a cloud folder and an external drive, and make sure the backup updates at the same time as the original. Store receipt images in the same structure, so that a search for one month finds everything in that month.
Test the backup occasionally by opening a file from the copy. A backup that cannot be opened is no help during a dispute or a tax question. Simple checks like this protect the household’s records and the time spent building them.
Keeping the Stack Small
A household money stack built from a spreadsheet, a notebook, a receipt folder and a shared calendar will serve most families well. Review it every few months, remove anything that is not used and keep the categories steady. A small, reliable stack makes money decisions calmer, and it keeps attention on the goals that the household actually cares about. Share the monthly summary with everyone who contributes to the household budget, so decisions are made together.